Identity Verification: The Layer Most QC Programs Underbuild
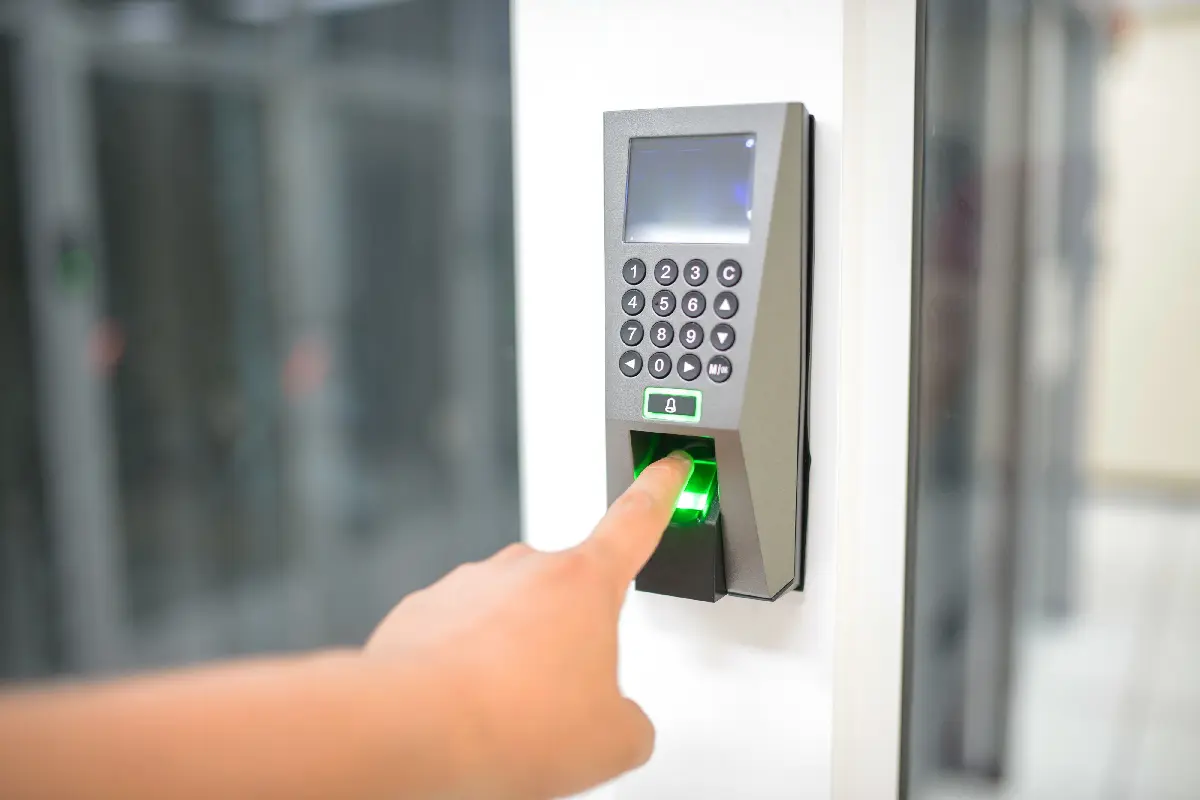
Identity verification is often the thinnest layer in an otherwise well-built QC program. Teams pour resources into income verification, appraisal review, and compliance checklists. But one simple question tends to get a quick glance instead of real scrutiny. Is the borrower actually who the file says they are? That gap is getting more expensive every year. It is showing up in agency findings, repurchase demands, and portfolio risk.
Table of Contents
Why Identity Verification Gets Treated as an Afterthought
Most QC programs were built around document accuracy rather than identity risk. For example, reviewers confirm that a Social Security number matches, check that a photo ID looks reasonable, and verify that signatures align across the file. These checks matter and always will. However, they were never designed to catch synthetic identities or stolen credentials. As a result, fraud rings can assemble borrower profiles using pieces of real identities
Quality Control and Quality Assurance leaders often assume identity fraud is rare enough to deprioritize. However, that assumption is aging poorly. Fraud schemes have grown more organized, and many now target the identity layer specifically because it receives the least scrutiny during a standard review.
Moreover, this is not just a mortgage industry problem. Identity fraud detection and know your customer, or KYC, compliance have become priorities across banking, lending, and insurance. As a result, mortgage QC teams are simply catching up to a standard that other financial sectors adopted years ago.
The Cost of a Thin Identity Verification Layer
A weak identity verification process rarely announces itself with one dramatic loss. Instead, it builds slowly. It shows up as repurchase demands, agency findings, and reputational exposure that stack up over time. When a loan defaults and an investor traces the file back to a fabricated or stolen identity, the QC program that missed it becomes part of the story.
Agency reviews increasingly ask a harder question. It is not just whether a defect existed. It is why the QC process failed to catch it before the loan closed. Programs that treat identity verification as a formality tend to struggle here. The corrective action that follows an agency finding can be costly. It can also take months to resolve.
What a Stronger Identity Verification Function Looks Like
Building a real identity verification layer means going past the surface checks most programs rely on today. It means cross-referencing multiple data points. Employment history, address history, phone and device signals, and document forensics all play a role. Document forensics can catch a manipulated file that would otherwise sail through. Treating verification services as their own discipline matters too. Never bury identity checks as a subtask within the general document review.
Some lenders are also rethinking where identity verification sits in the loan lifecycle. Catching an identity issue during a pre-funding review costs far less than uncovering it after closing. By then, the loan may already be sold or securitized. A well-structured post-closing QC audit still matters and always will. But identity checks belong earlier in the process whenever the file allows it. Front-loading identity verification also gives underwriting a chance to resolve a flag before it becomes a closed-loan problem.
What the Data and Regulators Are Telling Us
Identity-related fraud is not a fringe concern for QC and QA teams. The Financial Crimes Enforcement Network tracks suspicious activity tied to mortgage fraud closely. FINCEN reporting has repeatedly flagged identity theft as one of the fastest-growing categories in that data. The trend has held across multiple review cycles. That consistency suggests something important. This is not tied to a single bad actor or an unusual year.
For QC and QA leaders, that pattern is worth taking seriously. Regulators are tracking identity theft trends closely enough to report on them year after year. QC programs should be watching just as closely inside their own portfolios.
Making Identity Verification Part of the Program, Not a Side Task
The fix is not necessarily more headcount. It is not a longer checklist either. The solution is a shift in how identity verification is positioned inside the QC function. It deserves a seat next to income and asset verification as a core review category. Give it its own metrics. Provide it with its own findings trends. Give it its own path back into underwriting policy.
Programs that make this shift tend to notice something else change too. They gain the confidence to speak plainly with investors and agencies about identity risk. That confidence comes from real diligence, not a checked box.
Where QC Verify Fits In
QC Verify built its concierge quality control model with exactly this problem in mind. QC Verify is an agency-compliant audit and verification partner for mortgage QC and risk teams. The company pairs detailed QC reporting with hands-on verification support that applies the same rigor to identity checks as to income and asset reviews. Clients get more than a report. They get a QC partner who follows through on every layer of the file. That includes the identity layer that so many programs still underbuild.
If your QC program could use a closer look at how it handles identity verification, we would welcome the conversation. Reach out to the QC Verify team. Let’s talk through what a stronger verification layer could look like for your portfolio.